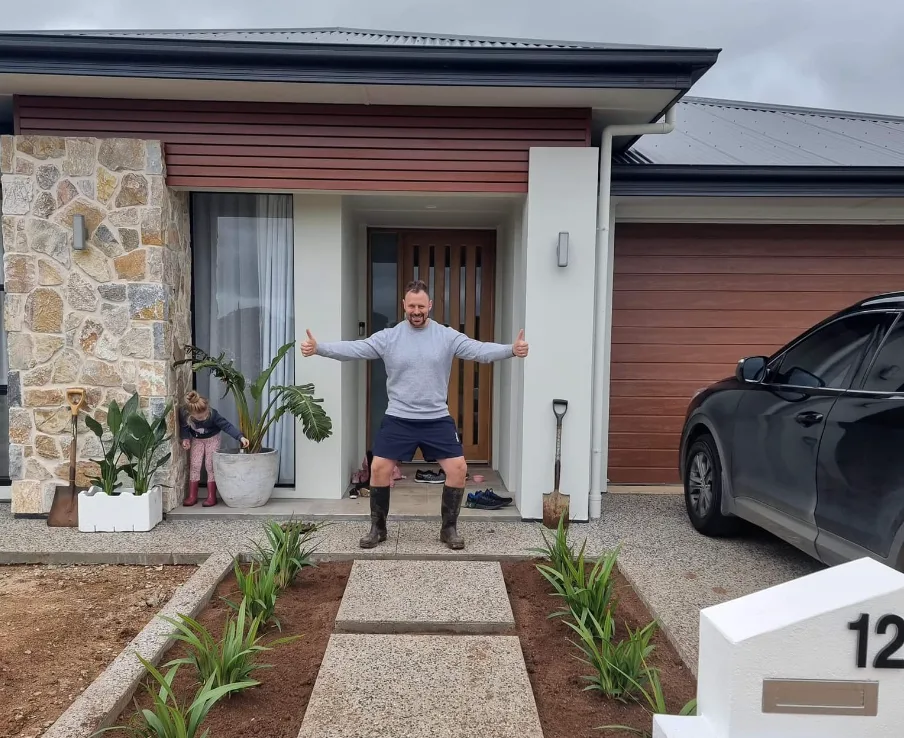
Serving Nindaroo
Mortgage Broker Nindaroo
Need a mortgage broker Nindaroo locals actually answer? Your Mortgage Broker Rural View arranges home loans across this growing Mackay Region pocket, matching your situation to credit policies that fit.
Looking for a Mortgage Broker in Nindaroo?
Banks assess Nindaroo against established-suburb checklists, yet this estate has just 78 dwellings and 285 recent approvals, which generic assessment routinely misses.
Home Loans We Arrange in Nindaroo
Five structures cover most situations here, alongside our construction loans and first home buyer loans pages:
Refinancing
Existing owners here refinanced years ago and never revisited the structure, yet nearly half of Nindaroo dwellings carry a mortgage, which makes a structured review worthwhile, because repayments, features and fees that suited one life stage rarely suit the next.
First Home Buyer Loans
Buying your first place around here means a house in a newer estate, and a range of deposit routes can work, from the federal guarantee to a guarantor, so we map the realistic paths before you commit to any contract.
Investment Property Loans
Strong household incomes and steady tenant demand across the northern beaches make this pocket attractive for investors, and lenders count rental income in different ways, so we present your application to the credit policies that treat your specific figures favourably.
Construction and Renovation Loans
Approval activity here sits high for a reason: land releases keep turning into builds, and a construction loan pays the builder in inspected stages rather than one lump, which protects you and keeps interest costs down while the work progresses.
Guarantor Loans
Family guarantee lending suits buyers chasing detached homes with generous floor plans, and can bridge a deposit gap without years of saving, though it places a mortgage over the guarantor's property, so they should obtain independent legal and financial advice.
What Makes Financing a Nindaroo Property Different
Just 78 dwellings stood here at last count, yet 285 approvals have flowed through since:
Housing Stock and Era
Ninety-three per cent of dwellings are separate houses and apartments are almost absent, so city-style density rules and floor-area minimums rarely bite, while young housing stock means valuations lean on recent estate sales rather than aged comparisons from older suburbs.
Valuations on New Builds
Fresh estates create a valuation quirk: comparable sales can be thin when a street has only just filled, and lenders order fuller evidence before approving, so we flag files early where the purchase price runs ahead of anything sold nearby.
Buyers With Bigger Budgets
Households here sit in the state's top income band and the most advantaged decile, so borrowing capacity is rarely the constraint; the conversations turn to structure, how a loan supports a future investment purchase or a bigger family build later.
A Split Ownership Mix
Owners being paid off and owners who finished sit nearly level, at close to forty-nine and forty-five per cent respectively, so this is both a refinance market and an equity market, and the right conversation depends on your exact position.
Common Situations We See in Nindaroo
Barely 255 residents, yet hundreds of recent approvals, means the borrowers here are not who you might guess:
Building the Family Home
Families upgrading into four or more bedrooms dominate, since roughly two-thirds of local homes offer that much space, and we regularly arrange construction funding for households trading up within the northern beaches rather than moving into established stock anywhere else.
When Fixed Terms End
Borrowers who locked rates during earlier cycles are watching terms expire, and a repayment that jumps several hundred dollars a month deserves a proper review, because the exit structure, fees and features all need scrutiny before you accept the revert.
Self-Employed Borrowers Nearby
Tradespeople and operators servicing local builds live here too, business income needs different evidence, and we match alt doc and low doc policies to how your accountant presents your figures instead of forcing your file down the standard payslip route.
Equity Sitting Idle
Long-term owners across the wider Mackay area hold substantial equity while repayments wind down, and some want a renovation, an investment deposit or a helping hand for adult children, each of which points to a different structure we can model.
How it works
Our Process
Here is what happens from first contact through to keys in hand:
- 1
Speak to a Broker
Your first conversation costs nothing at all and covers your goals, timeframe and current position, and we will tell you honestly whether broking suits your situation or whether going direct to a lender serves you better, before anything is signed.
- 2
Capacity and Options Assessed
We gather documents once, then assess serviceability against each relevant credit policy, because a figure that declines at one lender can pass at another, and we would rather test your file properly than submit it blind and hope for approval.
- 3
Options in Writing
Expect a written comparison of suitable loan structures, with fees, features and total costs laid out side by side, so the decision then rests on documented facts you can read clearly at your own pace, not a hurried sales pitch.
- 4
Application Through to Settlement
Once you choose, we lodge, chase conditions, coordinate the valuation and keep you updated at each milestone through to settlement, and then we check your very first repayment lands correctly before booking a review for twelve months down the track.
Why Choose Your Mortgage Broker Rural View in Nindaroo
Trust is earned with verifiable detail, as our About page explains, so here is what you can check:
A Named, Accountable Broker
You deal with Your Mortgage Broker Rural View, who is a credit representative under Connective Credit Services Pty Ltd, so the person advising you is identified and accountable, from call to settlement, and you can verify both the licence number and the representative number publicly online.
Fees Stated Upfront
Our fee and commission structure is published, so you can see what we receive and when, before you engage us, and we will always put the same figures in writing for your own file if you want them documented fully.
A Genuinely Wide Panel
Working across a genuinely wide panel of lenders rather than a single bank matters most where policy differs, and while no panel covers the entire market, breadth here gives your file a fair hearing across many different lenders' credit policies.
Process You Can Verify
Timelines, checkpoints and communication standards are published, so you know when your valuation is ordered, when conditions arrive and who is chasing what, and we actually commit to regular written updates rather than leaving you to wonder where things sit.
Licensing and Compliance
Credit regulation protects you, so here is a plain summary of our licence arrangements:
Credit Representative Status
Your Mortgage Broker Rural View operates as a credit representative of Connective Credit Services Pty Ltd, which holds Australian Credit Licence 389328, and our representative number is 370592, so you can trace every credit activity we perform back to a licensed and supervised licensee entity.
Responsible Lending Obligations
Before recommending any loan we must make reasonable enquiries about your requirements and financial situation, assess whether the loan is not unsuitable, and keep records of that assessment, which is why the document gathering stage is thorough rather than fussy.
Privacy and Your Data
Personal and financial information is collected only for providing credit assistance, handled under the Privacy Act, and never sold, and we will always explain exactly what gets shared with each lender before any single document leaves our hands for assessment.
How Complaints Work
If something goes wrong you can complain to us directly, escalate to our licensee, and take unresolved disputes to the Australian Financial Complaints Authority, an external and free dispute resolution service, and we will give you the details in writing.
Getting a Better Rate on Your Nindaroo Loan
The headline figure is one lever, and rarely the biggest, so these moves genuinely change total cost:
Review Before Deadlines Hit
A loan that suited you three years ago may no longer fit, and reviewing before a fixed term ends, before a renovation or before another purchase gives you room to restructure on your terms rather than react to a deadline.
Match Features to Habits
An offset account, a redraw facility or an extra repayment option only earns its keep if you actually use it, and paying an annual package fee for features sitting idle is a quiet leak we look for in every review.
Structure Before You Shop
How the loan is split, fixed, variable or offset matters more over a decade than small differences in the headline figure, and we model structures against your plans, because the option that looks tidy today can cost you flexibility tomorrow.
Helping Valuations Land Cleanly
When a valuation comes in short it can force a higher deposit or a repriced loan, and in a young estate where sales evidence is thin, preparing sales and contract details before lodgement improves the odds of one landing cleanly.
Where we work
Areas We Service
Beyond Nindaroo, Your Mortgage Broker Rural View helps borrowers across the Mackay Region, including Rural View, Bucasia, Eimeo and Blacks Beach.
Questions answered
Frequently Asked Questions
Do you meet clients in Nindaroo or work remotely?
Both. We meet by phone, video or in person around Nindaroo and the wider Mackay Region, and most clients start by video call.
What is the median price in Nindaroo right now?
We avoid quoting a figure, because Nindaroo is so new that settled sales are limited, and we would rather point you to current sourced data.
How long does home loan approval take?
From complete documents, assessment often runs three to ten business days depending on lender and loan type, with construction and guarantor files taking longer.
Can you help with a Nindaroo investment property?
Yes. With high local incomes and detached stock dominating, we match investment applications to lenders whose rental income policies suit your figures.
Do you charge a fee for your service?
Yes, transparently. We publish what we earn and when, and most home loan clients pay us nothing directly, because the lender pays commission.
Which lenders do you have access to?
We work with a panel of lenders spanning major banks, credit unions and non-bank lenders, though no panel covers the whole market, and we say so.
Mortgage broker for Rural View and the suburbs around it
Get in Touch
Call (07) 3523 7116 for a no-cost chat about your Nindaroo plans, or message us for a reply within a business day.